

Group Accident & Disability Insurance
Even the safest workplaces are not immune to accidents. When an employee is injured and unable to work, it affects not only their livelihood but also the company’s productivity and morale.
Group Accident & Disability Insurance bridges that gap — providing employees with a lump-sum benefit in the event of serious injury, and giving employers a reliable system of protection.
Who Needs Group Accident & Disability Insurance?
Group Accident & Disability Insurance is ideal for companies in Hong Kong that want to protect employees against the financial impact of serious accidents — whether they happen at work, during commutes, or in daily life. Even in low-risk office environments, …
Read More
accidents can occur unexpectedly, and the consequences can be significant for both the employee and their family.
This cover is valuable for businesses with internationally mobile employees with frequent travel, or operational exposure. It provides an affordable, high-impact layer of protection that strengthens employee confidence, improves retention, and reinforces your reputation as a responsible employer.
Possible Pitfalls We Help You Avoid
Group Accident & Disability policies vary widely, and the biggest problems usually come from unclear definitions. A common issue is misunderstanding what “disability” means — some policies pay only for permanent total disability, while others include partial disability or
Read More
temporary incapacity benefits. Without careful review, employers may think they have strong protection, only to find benefit payouts are limited.
Another frequent pitfall is restricted coverage scope. Some plans cover only working hours or work-related incidents, leaving employees unprotected outside the office. Expat Insurance helps secure true 24/7 cover where appropriate, especially for employees who travel regularly. We also address benefit limit weaknesses — low sums insured can create the appearance of protection without providing meaningful financial support.
These gaps often only become visible after an accident occurs. Expat Insurance helps arrange a policy that responds fairly and clearly when employees need it most.
Why Work With Expat Insurance?
Group Accident & Disability insurance is not just about “having a policy” — it’s about making sure the policy pays when needed, under realistic circumstances. The differences between insurers can be hidden in eligibility rules, definitions, and claims triggers, and …
Read More
those details determine whether an employee receives support or faces delays and disputes.
Expat Insurance helps structure the right benefit levels, with company coverage tiers, and definitions for your business. Options from leading insurers are compared and explained, simplifying decision-making for HR, and support implementation so staff understand what is included. When claims happen, we assist throughout the process and liaise with insurers to achieve results and claim payments — protecting both your team and the company’s peace of mind.
What Does Typical Cover Include?
Group Accident & Disability Insurance typically provides lump-sum benefits for accidental death, permanent disability, and partial disability based on medical assessment. Many plans can also include temporary incapacity support during recovery periods, accidental medical
Read More
reimbursement for immediate treatment, and 24-hour worldwide coverage — including outside working hours depending on the plan design.
Optional enhancements may include family or dependent add-ons, higher benefit tiers for senior staff, and broader definitions to ensure fair coverage outcomes. Done properly, this cover gives employees confidence that they and their families are financially protected — and gives employers a practical, reliable way to demonstrate real care.
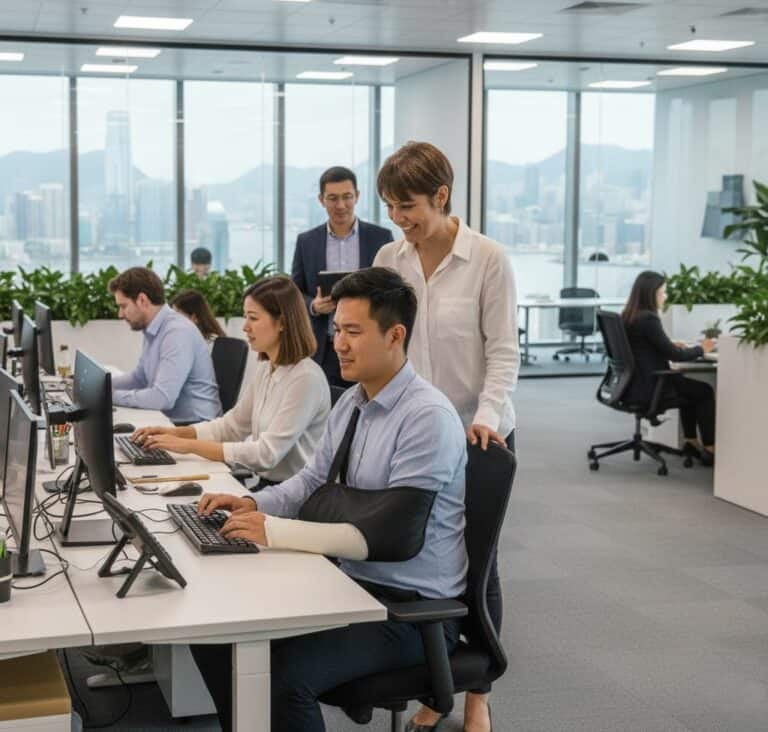
What the benefits actually pay
Accident and disability cover does something no medical plan does: it pays cash to the employee rather than to a hospital. Treatment is the health plan’s job. This one answers the consequence of an injury — the months of lost income, the adaptations to a home, the years of reduced earning that follow a serious event, and the effect on the health of everyone else in the household.
The money arrives in one of two shapes. A lump sum is paid against a scale: a fixed percentage of the sum insured for the loss of a hand, a limb, sight, hearing. It is paid once, on assessment, and it is not related to salary. An income stream works differently — a monthly amount, usually a proportion of earnings, paid while the employee cannot return to their job and ceasing when they do.
Most employer schemes carry both, and the gap between them is the single thing worth understanding before anyone signs. A generous lump sum does nothing for someone who is off for eighteen months and then recovers. A monthly income does nothing for someone permanently disabled who needs to rebuild a house around a wheelchair. The two are not alternatives; they answer different outcomes, and an employer who buys one and assumes it does the work of the other has a gap they will not see until somebody claims.
Cover for employees with disabilities
A staff scheme accepts people an individual insurer might decline, because nobody is assessed one by one. An employee who already has a disability is generally admitted on the same terms as everyone else — which is why company cover matters most to the people least able to buy it privately.
The limit is that a condition already present when the scheme starts is normally excluded from a claim arising out of it. Someone with restricted mobility is still covered for an unrelated accident; they are not covered for a deterioration of the thing they already had. That is a narrower exclusion than most employers assume.
Where an employee needs certainty about an existing condition, the honest route is to obtain a personal assessment rather than rely on an assumption, because individual disability terms differ sharply between carriers. Some will accept a condition with a loading, some with an exclusion, some not at all, and the answer differs enough between them that it is worth putting the question to more than one. It is worth asking before the situation is urgent rather than after.
None of this is unusual, and none of it should be guesswork. An employer who knows in advance how their arrangement treats disabilities, and how it treats the health of people already living with them, is in a far better position than one who finds out during a claim, and it costs nothing to establish it while everybody is well.
Let's Get Your Insurance Done Right
Group Accident & Disability Insurance can be complex — benefits vary widely between insurers, and eligibility terms can be confusing. We simplify everything.
We start with your workforce structure.
We analyse employee roles, travel frequency, and exposure to risk.
We customise your plan.
We match benefit levels and coverage tiers to your company’s policies.
We manage implementation.
We coordinate policy setup, enrolment, and ongoing communication.
We provide claim assistance.
We handle employee claims, insurer negotiation, and ensure quick payouts.
CALL US TODAY
How Can We Help you?
Fill in your details, we’ll be in touch to answer your questions. No hard sell. Just the friendly help you need. We’ll get back to you to you within 24 hours. Or on the next business day if it’s now after hours.
Where insurance coverage stops
The wording of a disability policy, not the sum insured, decides what a disabled employee actually receives. Disability coverage that reads generously on a benefit summary is frequently narrow in the contract behind it. Three definitions do most of the work, and an employer who has not read them is buying on faith.
The first is what counts as disability at all. A contract written around “own occupation” pays when the employee cannot do the job they held. One written around “any occupation” pays only when they cannot do any job at all for which they are reasonably suited — a far higher bar, and the difference between a surgeon who can no longer operate being paid and being declined.
The second is when payment begins. There is almost always a deferred stretch, commonly thirteen or twenty-six weeks, during which the employer or the employee carries the cost. The third is how long it runs: some contracts pay for two years, some to retirement age. Those three numbers, more than the headline, determine whether the health of a household survives a serious injury.
The limitations worth knowing
Pre-existing conditions. Anything present before the scheme started is typically outside a claim arising from it, usually for the first year and sometimes permanently. It is the exclusion that most often surprises a disabled employee at the worst moment.
The deferred stretch. Nothing is paid during it. Where an employer offers sick pay the two should be aligned, so that one begins as the other ends rather than leaving a gap in income.
Mental health. Many contracts cap claims arising from psychiatric conditions at two years, even where the rest of the contract runs to retirement. Given how many long-term absences fall into this category, it is worth reading before you need it.
Where and when. Some schemes answer accidents only during working hours or on the employer’s premises. Others cover the employee anywhere in the world, at any hour, which matters most for staff whose health or existing disabilities make travel harder. The premium difference is smaller than most people expect, and the practical difference is enormous.
We Ensure Professional Insurance Services
Need Other Insurance Products?
Medical Insurance
Comprehensive international medical cover for individuals, families and businesses — hospital, surgical, maternity, wellness, outpatient and dental.
Corporate / Group
Flexible group medical and life plans that promote employee well-being, support long-term business success and improve staff retention in Hong Kong.
Business Insurance
Cover for losses from damage to contents, property and stock plus income loss, public liability and Employees' Compensation for business resilience.
Property Insurance
Protect your home and contents from fire, theft, typhoons, water damage, accidental damage and public liability for your complete peace of mind.
Life Insurance
Long-term financial security for your family — covering debts, mortgages and children's education so the unexpected never derails your plans in Hong Kong.
Which payment answers which outcome
An injury produces several different problems at once, and each is answered by a different part of the arrangement. A group disability benefit is only one of them, and it is rarely the part that pays for treatment. Reading them side by side is the fastest way to see where an employer is genuinely protected and where a disabled employee would be left carrying the consequence themselves.
| What happens | What a staff scheme normally answers | What is left over | Read more |
|---|---|---|---|
| Treatment after an accident | Reimbursement of immediate medical costs, up to a limit | Ongoing care once the accident benefit is exhausted | Staff health schemes |
| A few weeks off | Usually nothing — the deferred stretch has not elapsed | Sick pay, or the employee’s own savings | Personal accident plans |
| Months unable to do the job | A monthly income, once the deferred stretch ends | The shortfall between the benefit and full earnings | Personal health plans |
| Permanent loss of a limb or sight | A lump sum against a fixed scale of percentages | Home adaptations and equipment beyond that sum | Accident cover |
| A serious diagnosis, no accident | Often nothing — accident wordings require an accident | The whole cost, unless illness cover is held | Critical illness plans |
| Death of an employee | A lump sum to the estate or nominated dependants | Longer-term support for the household | Death-in-service arrangements |
| When the employee leaves | Everything stops on the final day of employment | All of it, unless personal cover is already in place | Personal term life plans |
An injury at the workplace also engages a separate, compulsory obligation in Hong Kong. Employees’ compensation is required by law and answers injury arising out of employment; this arrangement is voluntary and answers a great deal more. The same review usually takes in business travel protection and, where staff are sent abroad, international health plans, because a gap in one is frequently closed cheaply by another.
Our Simple Process
Talk to us about your needs
We learn your budget, lifestyle, and health priorities.
Compare your best options
We present suitable plans side-by-side in clear language.
Get you insured quickly
We handle the applications, forms, and negotiations.
Stay with you long-term
Each year, we review your policy and help with claims.
testimonials
Why Our Clients Are Satisfied
Our service consistently exceeds expectations. But don’t just take our word for it—here’s what our customers say!


How a disabled employee is assessed
A disability claim is decided by evidence, not by sympathy, and the evidence is medical. The treating doctor completes a report describing the condition, the restrictions it imposes and the expected duration. The insurer’s own medical officer reads it against the contract wording, and where the two disagree an independent assessment is arranged.
For a lump sum the question is narrow: does the loss fall on the scale, and at what percentage — that is, is this a covered disability under the contract as written. Those scales are published in the contract and vary less between carriers than people expect. For an income claim the question is broader and is revisited — the employee is reassessed periodically, and payment continues only while the restriction does.
Two things make the difference between a smooth disability claim and a slow one. The first is early notification: telling the insurer at the point of injury rather than at the end of the deferred stretch. The second is a treating doctor who has been asked for the right report. Neither is complicated, and both are the sort of thing an employer should not be discovering for the first time in the middle of a crisis, when the employee’s health is already the harder problem.
What slows a claim down
Late notification. Most contracts require notice within a defined number of days. Reporting an injury weeks later, once it becomes clear the employee will not be back, is the most common cause of a disputed disability benefit.
A report that answers the wrong question. A medical certificate saying someone is unwell is not evidence of incapacity for a specific occupation. The insurer needs restrictions, not a diagnosis alone.
Salary that cannot be evidenced. Income benefits are calculated from earnings at a defined date. Where pay is variable, or bonuses form much of it, the definition in the contract needs checking before a claim rather than during it.
Leaving mid-claim. Cover ends with employment. A disabled employee whose contract is terminated during the deferred stretch can find the claim ends with it, which is one of the strongest arguments for holding personal protection alongside.
An unrelated exclusion. Hazardous pursuits, aviation other than as a passenger, and injury sustained while committing an offence are standard carve-outs. They rarely matter, and when they do they matter completely.
Choosing the right level of protection
The sums are usually expressed as a multiple of salary, and the multiple is where employers most often default to the market rather than to their own circumstances. Two or three times annual earnings is common for a lump sum, frequently with an income rider attached; sixty to seventy-five per cent of salary is common for the income stream itself. Neither number is right or wrong until you know who is being insured.
A young team with no dependants and no mortgages has a different exposure from a senior group with both. A business whose people travel constantly, work at height or drive for a living carries a different risk from one that does not, and so does one employing people with existing disabilities. The right answer follows the actual exposure, and arriving at it takes an hour with someone who has read a great many of these contracts.
Renewal is where the value is won. Carriers reprice on claims experience, so a single event can produce an increase that has nothing to do with the wider market. That is the moment to test the arrangement against alternatives rather than accept the invitation, and it is a conversation to start sixty to ninety days out. In Hong Kong the public safety net is narrow — a disability allowance exists, but it pays a modest monthly sum and was never designed to replace earnings — so what the employer provides is, in practice, most of what an employee has, and the only reliable access to real money after a serious injury. Health benefits pay the hospital; this pays the household.
What to check before you sign
- Whether disability is defined by own occupation or by any occupation
- How many weeks the deferred stretch runs, and how it aligns with sick pay
- How long payments continue — a fixed term, or to retirement age
- Whether psychiatric conditions carry a shorter limit than everything else
- What the scale of percentages pays for the losses most relevant to your people
- Whether the scheme answers accidents only at the workplace or worldwide, around the clock
- How a pre-existing condition is treated in the first year and afterwards
- Whether salary is defined as basic pay or includes bonus and allowances
- What notification deadline applies, and who in the company owns it
- How the contract treats employees with existing disabilities, in year one and after
- Whether the sums insured have been reviewed since salaries last moved
- Whether leavers can convert to personal accident cover without fresh underwriting
Illustrative Examples — How the Right Cover Changes the Outcome
An employer scheme can look comprehensive and still cover only part of a large hospital bill. Checking the limits before you need them is what shows whether there is a gap worth closing.
Waiting periods — not price — often decide between two policies that otherwise look the same. Planning ahead of a life change is what keeps the better option open.
Where you want to be treated changes which policy suits you more than most people expect. Cover that stops at the border is a very different product from cover that travels with you.
These are not isolated cases but common realities in Hong Kong, where unexpected medical events can swiftly become financial burdens. Protection versus exposure often comes down to the policy you choose.
Frequently Asked Questions
What insurance is best for disability?+
Does Hong Kong have disability benefits?+
Is ataxia a disability?+
What are the 7 types of disability?+
Can an employee who already has a disability join the scheme?+
Is this the same as employees’ compensation?+
What is the difference between a lump sum and an income benefit?+
Does the cover apply outside working hours?+
What happens if an employee leaves while a claim is running?+
Protect What Matters With Confidence
Don’t wait until an emergency strikes to realise your coverage isn’t sufficient. With expert and professional guidance from Expat Insurance, you can be certain that your business, health, home, and future are fully protected.
Where this fits
Group Accident & Disability in Hong Kong
This cover sits inside a wider programme. These are the policies most often arranged alongside it, and the page each one is explained on.
Related cover

